NEWS·SEPTEMBER 2026
Recent proposals to loosen planning regulations around railway stations present a strategic opportunity for developers and investors to unlock transit-oriented residential projects across England.

NEWS·SEPTEMBER 2026
Recent proposals to loosen planning regulations around railway stations present a strategic opportunity for developers and investors to unlock transit-oriented residential projects across England.

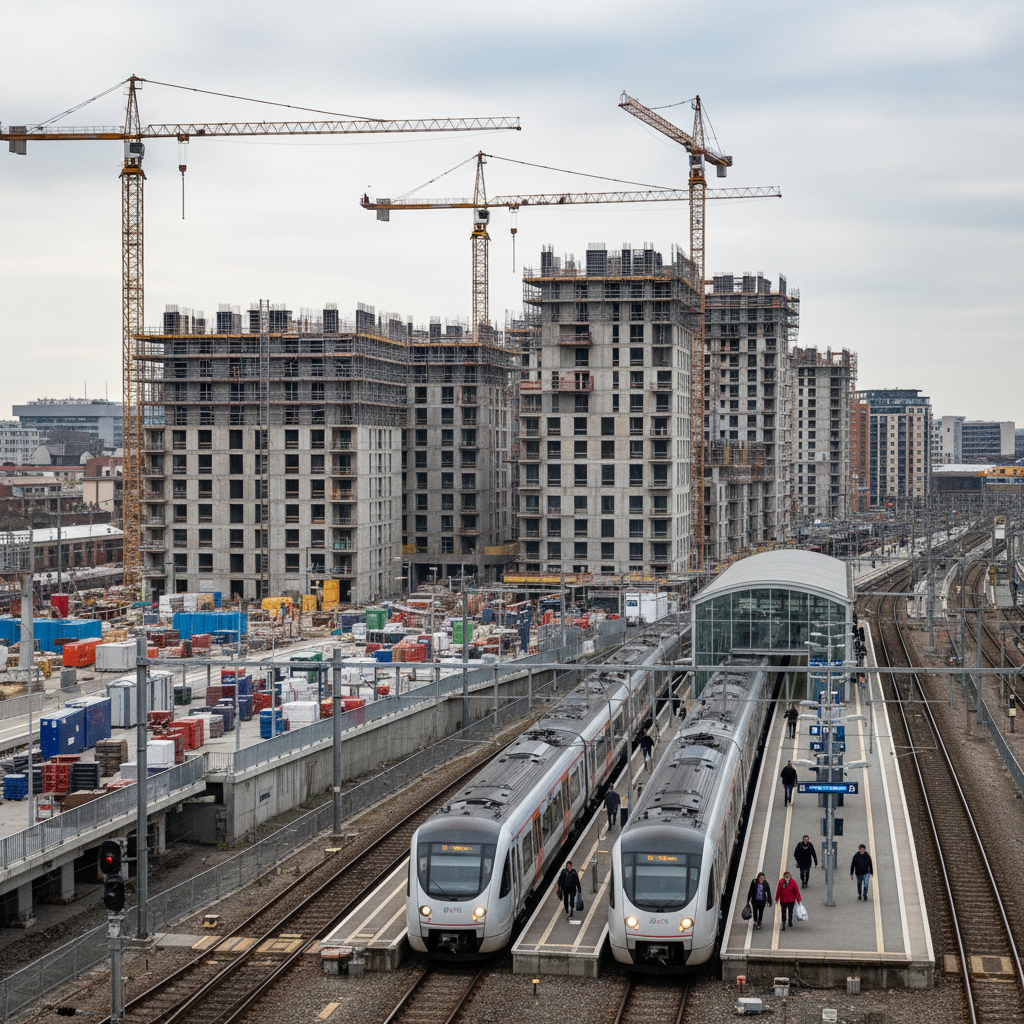
The UK press has reported a forthcoming relaxation of planning regulations in England, specifically targeting land adjacent to railway stations and transport hubs. This policy shift is designed to accelerate housing delivery in strategically important, transit-oriented locations. For the UK real estate sector, this represents a significant catalyst for urban regeneration, potentially unlocking dormant development sites and recalibrating land values around key transport infrastructure.
The drive to increase residential density near transport nodes is a logical response to the ongoing national housing shortage. By focusing new development around existing infrastructure, policymakers aim to deliver sustainable growth while reducing reliance on private vehicles.
Reported proposals suggest a presumption in favour of development for residential projects situated within a specified radius of railway stations. This loosening of the rules is expected to reduce the friction often experienced during the local planning process. It will allow developers to bring forward high-density schemes with greater certainty and at a faster pace.
A relaxation in national planning policy will inevitably alter the dynamics of the commercial land market. Sites that were previously considered unviable due to strict local density restrictions or historical planning constraints may now present highly lucrative opportunities for large-scale residential delivery.
We anticipate a swift recalibration of land values in these targeted commuter zones. Landowners and institutional investors will need to reassess the gross development value of their assets under the new parameters. Furthermore, increased competition for these prime sites will likely drive up initial acquisition costs. This makes early site identification and discreet off-market negotiations critical for developers looking to secure a competitive advantage.
For active developers, the immediate focus must shift towards rapid site identification and rigorous feasibility analysis. Assessing the newly permitted capacity for increased density, taller structures, or reduced parking requirements will be essential to maximising the overall potential of a site.
The GLPG Agency team is actively advising clients on the acquisition and disposal of strategic sites positioned to benefit from these regulatory changes. Our focus remains on identifying off-market opportunities and structuring complex acquisitions that mitigate initial planning risk while capturing the long-term upside of increased density allowances.
Capitalising on these opportunities will also require robust and flexible funding strategies. The GLPG Capital Advisory division is working closely with institutional lenders who look favourably on transit-oriented developments. We are currently structuring debt and equity solutions that align with the revised planning timelines and the increased scale of these projects.
Higher density schemes inevitably trigger complex Section 106 obligations and affordable housing requirements. The integration of affordable tenures will remain a critical component of any successful planning application, even within a relaxed national regulatory framework.
Our Affordable Housing division is actively assisting developers in navigating these specific requirements. By engaging early with registered housing associations and local authorities, we help our clients negotiate viable S106 agreements. This ensures that projects satisfy local policy demands without compromising the underlying profitability of the development.
Market participants should closely monitor the formal publication of these planning reforms to understand the exact definitions of qualifying transport hubs. The specific radius applied to these zones will be the most critical metric to watch. The detail within the impending legislation will dictate the true scale of the opportunity across England. Proactive developers and investors should already be mapping potential sites ahead of the official policy implementation.
NEWS·SEPTEMBER 2026
Recent proposals to loosen planning regulations around railway stations present a strategic opportunity for developers and investors to unlock transit-oriented residential projects across England.

The UK press has reported a forthcoming relaxation of planning regulations in England, specifically targeting land adjacent to railway stations and transport hubs. This policy shift is designed to accelerate housing delivery in strategically important, transit-oriented locations. For the UK real estate sector, this represents a significant catalyst for urban regeneration, potentially unlocking dormant development sites and recalibrating land values around key transport infrastructure.
The drive to increase residential density near transport nodes is a logical response to the ongoing national housing shortage. By focusing new development around existing infrastructure, policymakers aim to deliver sustainable growth while reducing reliance on private vehicles.
Reported proposals suggest a presumption in favour of development for residential projects situated within a specified radius of railway stations. This loosening of the rules is expected to reduce the friction often experienced during the local planning process. It will allow developers to bring forward high-density schemes with greater certainty and at a faster pace.
A relaxation in national planning policy will inevitably alter the dynamics of the commercial land market. Sites that were previously considered unviable due to strict local density restrictions or historical planning constraints may now present highly lucrative opportunities for large-scale residential delivery.
We anticipate a swift recalibration of land values in these targeted commuter zones. Landowners and institutional investors will need to reassess the gross development value of their assets under the new parameters. Furthermore, increased competition for these prime sites will likely drive up initial acquisition costs. This makes early site identification and discreet off-market negotiations critical for developers looking to secure a competitive advantage.
For active developers, the immediate focus must shift towards rapid site identification and rigorous feasibility analysis. Assessing the newly permitted capacity for increased density, taller structures, or reduced parking requirements will be essential to maximising the overall potential of a site.
The GLPG Agency team is actively advising clients on the acquisition and disposal of strategic sites positioned to benefit from these regulatory changes. Our focus remains on identifying off-market opportunities and structuring complex acquisitions that mitigate initial planning risk while capturing the long-term upside of increased density allowances.
Capitalising on these opportunities will also require robust and flexible funding strategies. The GLPG Capital Advisory division is working closely with institutional lenders who look favourably on transit-oriented developments. We are currently structuring debt and equity solutions that align with the revised planning timelines and the increased scale of these projects.
Higher density schemes inevitably trigger complex Section 106 obligations and affordable housing requirements. The integration of affordable tenures will remain a critical component of any successful planning application, even within a relaxed national regulatory framework.
Our Affordable Housing division is actively assisting developers in navigating these specific requirements. By engaging early with registered housing associations and local authorities, we help our clients negotiate viable S106 agreements. This ensures that projects satisfy local policy demands without compromising the underlying profitability of the development.
Market participants should closely monitor the formal publication of these planning reforms to understand the exact definitions of qualifying transport hubs. The specific radius applied to these zones will be the most critical metric to watch. The detail within the impending legislation will dictate the true scale of the opportunity across England. Proactive developers and investors should already be mapping potential sites ahead of the official policy implementation.