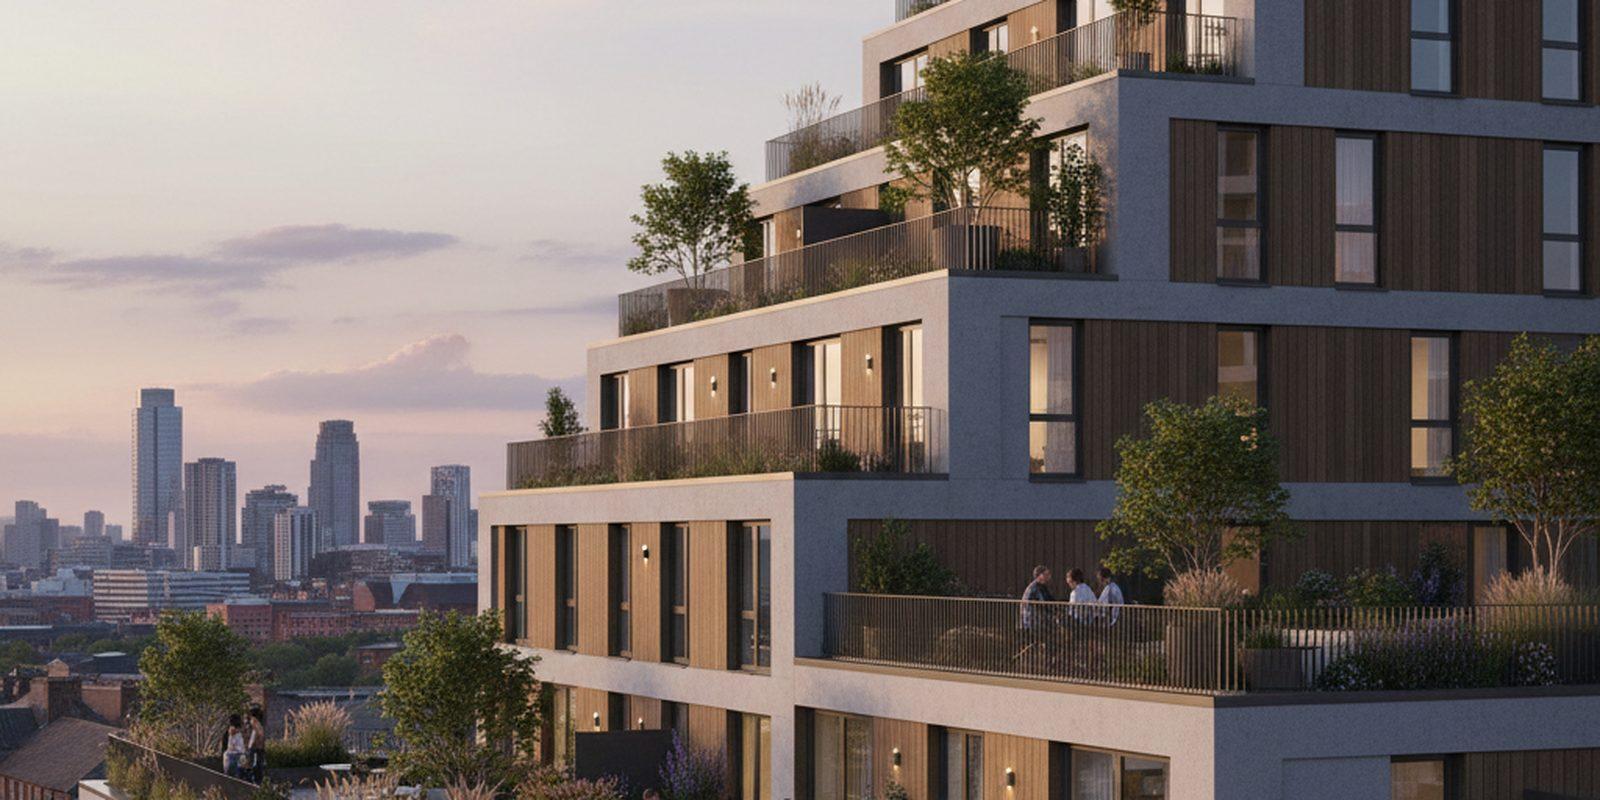
Whatever the final tally, the direction is unmistakable. The sector attracted roughly a tenth of all UK real estate investment last year, against a long run average nearer 5%, and the pipeline of schemes under construction remains the deepest in Europe.
The structural drivers
Three forces are compounding. Chronic undersupply of rental homes as smaller landlords exit ahead of the Renters' Rights Act. Institutional demand for inflation linked, long duration income. And a planning system increasingly supportive of high density residential in town centres and around transport hubs.
Geographically, the growth story has shifted beyond London. Manchester, Birmingham, Leeds and Bristol all saw record years for BTR investment, and single family housing, the suburban counterpart to city centre towers, emerged as the fastest growing part of the market.
The Renters' Rights Act, now law, is widely seen within the sector as an accelerant rather than a threat. Professional operators already work to standards the legislation makes universal, and consolidation of stock from exiting private landlords adds opportunity.
We expect 2026 to match or exceed last year, with forward funding of new development the area to watch as construction cost inflation finally eases.